
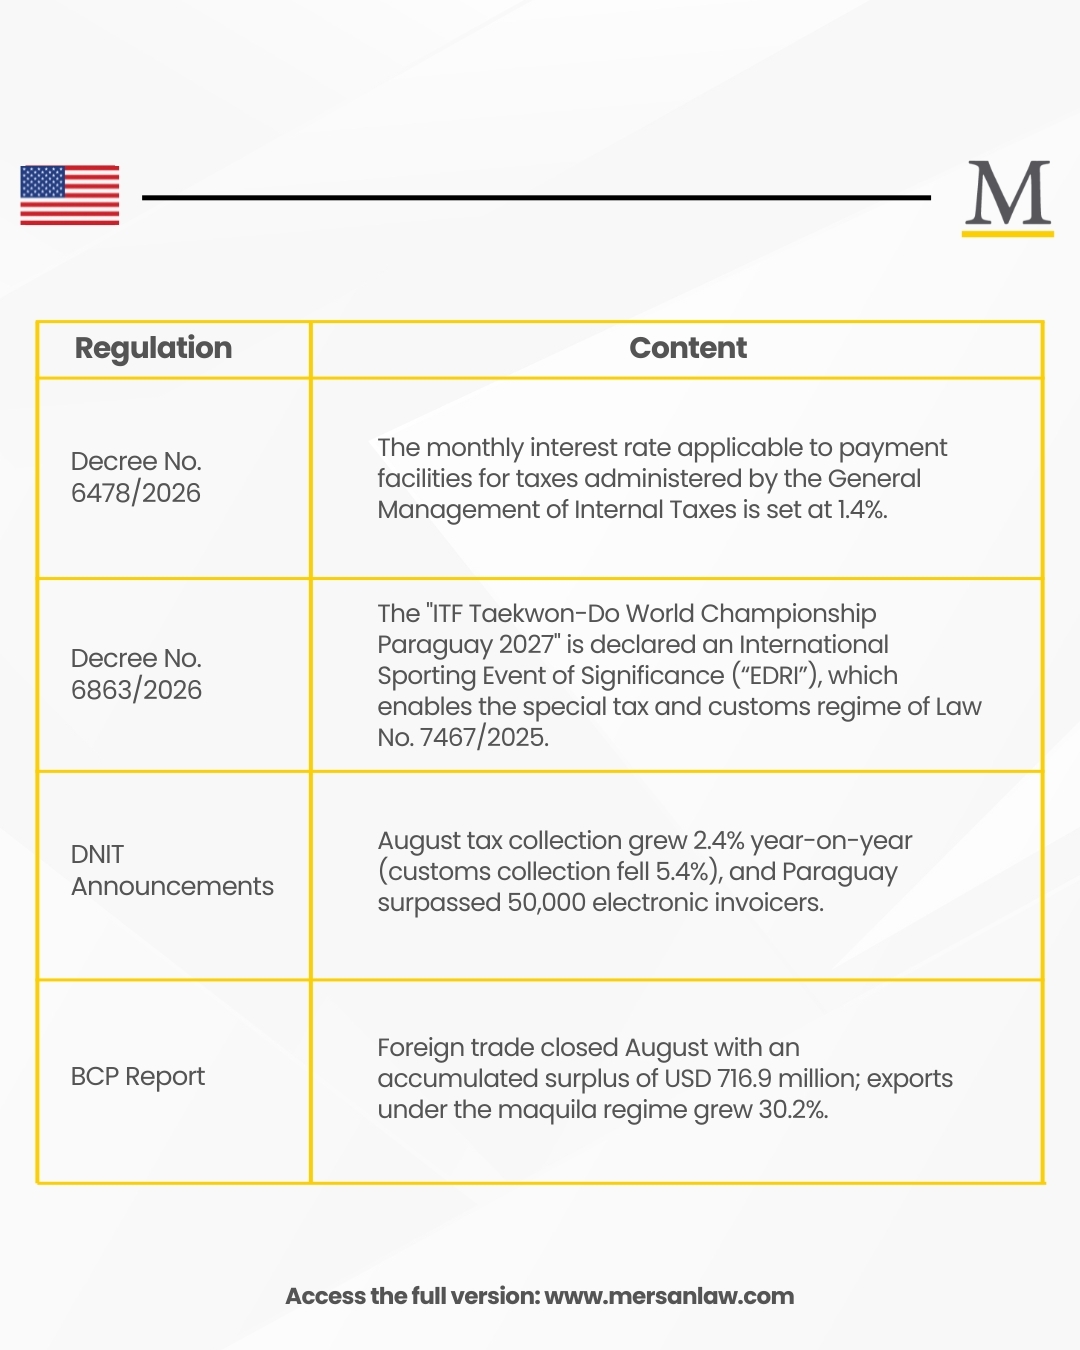
► Decree No. 6478/2026 – The monthly interest rate applicable to payment facilities for taxes administered by the General Management of Internal Taxes is set at 1.4%.
Through Decree No. 6478 of July 31, 2026, the Executive Branch set at 1.4% per month the interest rate that the National Directorate of Tax Revenue ("DNIT") charges when granting payment facilities (installment plans) for taxes administered by the General Management of Internal Taxes ("GGII"). The decree entered into force on September 1, 2026, and repeals Decree No. 5028/2021. Although it is dated July, we include it in this edition because it took effect in September and was only published and disseminated by the DNIT on September 14.
The legal basis is Article 161 of Law No. 125/1991, which mandates the Executive Branch to set this rate annually and requires it to be lower than the late-payment surcharge. That surcharge, provided for in Article 171 of the same law, is set at 1.5% per month by Decree No. 10.768/2013. The new rate complies with that cap, but the margin between paying a debt in installments and paying it with the late-payment surcharge is reduced to only 0.1 percentage point per month.
The rate applies to payment facilities granted as of September 1, 2026; therefore, it does not reach plans granted previously. According to the DNIT, the measure seeks to bring the cost of installment plans closer to financial market conditions and to prevent financing with the Tax Authority from being cheaper than financing with banks. In practice, before applying for a payment plan, it is advisable to compare its cost with that of available bank credit.
► Decree No. 6863/2026 – The "ITF Taekwon-Do World Championship Paraguay 2027" is declared an International Sporting Event of Significance.
Through Decree No. 6863 of September 9, 2026, the Executive Branch declared the ITF Taekwon-Do World Championship, to be held in Asunción from October 17 to 24, 2027, an International Sporting Event of Significance ("EDRI"). The declaration also covers the preparatory, operational and official activities linked to the event during 2026 and 2027, such as qualifying tournaments, congresses and training camps.
The declaration by decree is the prerequisite for applying the special regime of Law No. 7467/2025, which provides, among other benefits, for: (a) the exemption from taxes levied on the definitive importation of sporting goods necessary for the event; (b) the temporary admission of equipment and implements free of fees, charges and guarantees, with full exemption if they are subsequently donated to the National Sports Secretariat ("SND") or to entities recognized by it; (c) the exemption on the importation of certain goods for exclusive use at the event; and (d) the exemption from income taxes and value added tax ("VAT") on income earned, in connection with the EDRI, by the organizing entities and by non-resident athletes and other participants.
The procedure for accessing these benefits is regulated by DNIT General Resolution No. 32/2025 and is processed through the Marangatu system (Tax Exemptions module – "Franquicias Fiscales"), with an active Taxpayer Registry (RUC) number, up-to-date tax compliance and the list of goods approved by the SND. One point to bear in mind: that resolution requires beneficiaries to appear on the list included in the decree declaring the EDRI, and Decree No. 6863/2026 does not include such list, as it is limited to declaring the event and instructing the enforcement authorities. Therefore, a supplementary act identifying the organizing entity and the other beneficiaries will likely be required before the exemptions can be requested.
► DNIT Announcements – August Tax Collection and Progress in Electronic Invoicing.
According to the report published by the DNIT on September 8, tax collection for August 2026 amounted to G. 3,115,781 million (USD 527.8 million), 2.4% higher than in August 2025. The GGII grew 9.3%, driven mainly by VAT, while the General Management of Customs fell 5.4%, as the appreciation of the guaraní reduced the local-currency taxable base of imports. On a cumulative basis from January to August, tax collection totaled G. 28,932,849 million, 2.1% higher than in the same period of 2025.
Furthermore, on September 11 the DNIT reported that Paraguay surpassed 50,000 taxpayers enabled as electronic invoicers in the National Integrated Electronic Invoicing System ("SIFEN"). Small taxpayers account for 88.6%, and Asunción, Central and Alto Paraná concentrate 75.5% of the total. The figure reflects the effect of the successive designations of mandatory electronic invoicers ordered by the DNIT, such as DNIT General Resolution No. 52/2026.
► BCP Report – Foreign Trade through August 2026.
The foreign trade report of the Central Bank of Paraguay ("BCP") released in September shows that, between January and August 2026, exports reached USD 14,025.3 million (+24.7% year-on-year) and imports USD 13,308.4 million (+13.9%), with an accumulated surplus of USD 716.9 million, compared to a deficit of USD 437.8 million in the same period of 2025.
Growth is explained mainly by soybeans, whose exports increased 45.9% in value, while beef declined 7% (USD 1,297.7 million). Re-exports totaled USD 3,523.9 million and exports under the maquila regime reached USD 1,012.3 million, with growth of 30.2%, which confirms the increasing weight of this regime in the trade balance.
If your company needs advice on any of these topics, contact us: our Tax Law practice is ready to assist you.
 Español
 English
 Português do Brasil